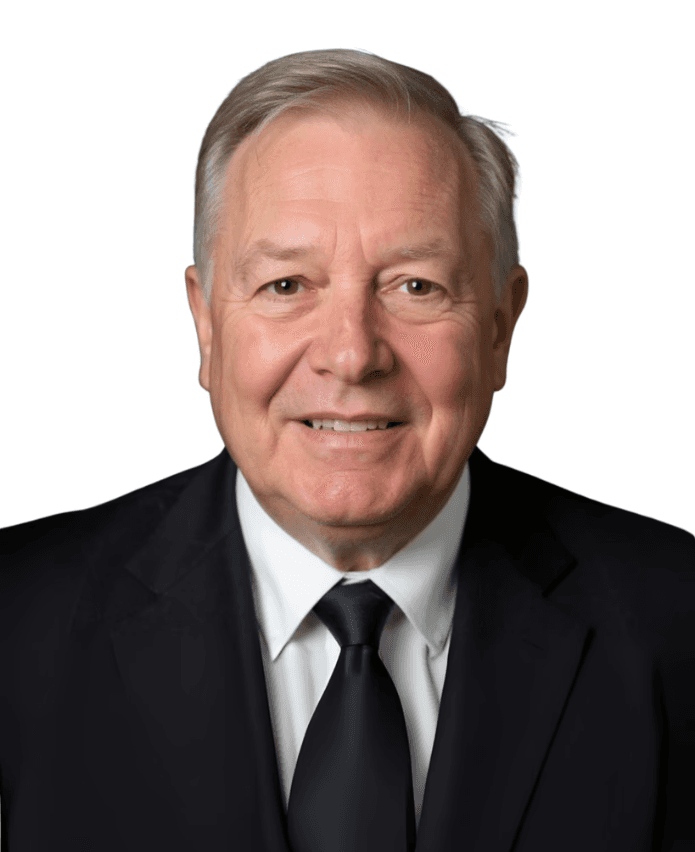
Tom Jarrett, Primis — Best Physician Mortgage

Jessica Hegge
TLDR
Tom Jarrett (NMLS 742280) is a physician mortgage specialist with Primis Bank serving Arizona and Texas.
With 25+ years in financial services, he focuses on graduating residents and new attendings navigating their transition year.
Primis offers no PMI, up to 100% financing, and underwriting based on expected/future income.
"Your first attending year is a transition year — the income changes fast, and the financial decisions feel bigger than ever." That's how Tom Jarrett (NMLS 742280) describes the borrowers he serves. With over 25 years in financial services, Tom specializes in helping graduating residents and new attendings buy with confidence through Primis Bank.
"Physicians are often stronger borrowers than their current financial picture may suggest," Tom told Dr. Home Finance — and much of his job is proving that to underwriting before a relocation deadline forces the issue.
Who Tom Jarrett works with
Tom serves physician borrowers in Arizona and Texas — working with residents, fellows, and attendings across a broad range of medical and allied-health designations (MD, DO, DDS, DMD, DPM, DVM, PharmD, CRNA, NP, PA).
The Primis Bank physician program
The Primis Bank program is built around doctors' timelines:
No private mortgage insurance (PMI) at listed LTV tiers
Up to 100% financing to $1,000,000; 95% to $1,500,000
Underwriting based on expected/future income, not just current DTI
A broad list of eligible medical and allied-health professions
The job hasn't started? That's not a dealbreaker.
One physician came to Tom preparing to relocate for a new attending position — limited savings, significant student debt, and a salary that hadn't started yet. Tom reviewed the signed employment contract, identified a physician program that could qualify the borrower on that future income, and the physician was approved to buy before the first paycheck arrived. For doctors facing a relocation deadline, that timing can reshape the entire move.
When a physician mortgage isn't the right call
Tom specializes in physician lending but also evaluates conventional and jumbo options — and compares them rather than assuming the physician loan always wins. He walks borrowers through fixed- versus adjustable-rate structures as rates move, with the goal of financing the physician understands and can comfortably manage.
Why work with a specialist
Offering physician mortgages and specializing in them are not the same thing. "A true physician mortgage specialist understands the full journey from residency and fellowship into an attending role," Tom explains. A specialist already knows how underwriting treats student loans, future income, and contract-based pay — which prevents avoidable delays. For the fundamentals, see our guide to how physician mortgages work.
Start early — before the moving truck
Tom's advice on when to begin? "As soon as possible." Reviewing the employment agreement and financials before you're under contract gives the whole team time to line up the closing around your start date.
Get connected with Tom Jarrett
Financing a home in Arizona and Texas? Get matched and Dr. Home Finance will connect you.
Frequently Asked Questions
Which states does Tom Jarrett serve?
Tom Jarrett serves physician borrowers in Arizona and Texas.
What does the Primis Bank physician program offer?
No PMI at listed LTV tiers, up to 100% financing (up to $1,000,000; 95% up to $1,500,000), and underwriting based on expected/future income rather than only current DTI.
Can Tom qualify me before my new job starts?
Yes. Certain physician programs allow eligible borrowers to qualify on an acceptable signed employment contract before the first paycheck — Tom reviews the contract and lines up the approval around your start date.
Dr. Home Finance is an educational and lender-matching resource and is not a mortgage lender. Loan programs, rates, and terms vary by borrower, bank, and state and are subject to change. Nothing here is an offer to lend.
Get matched with a physician mortgage lender